
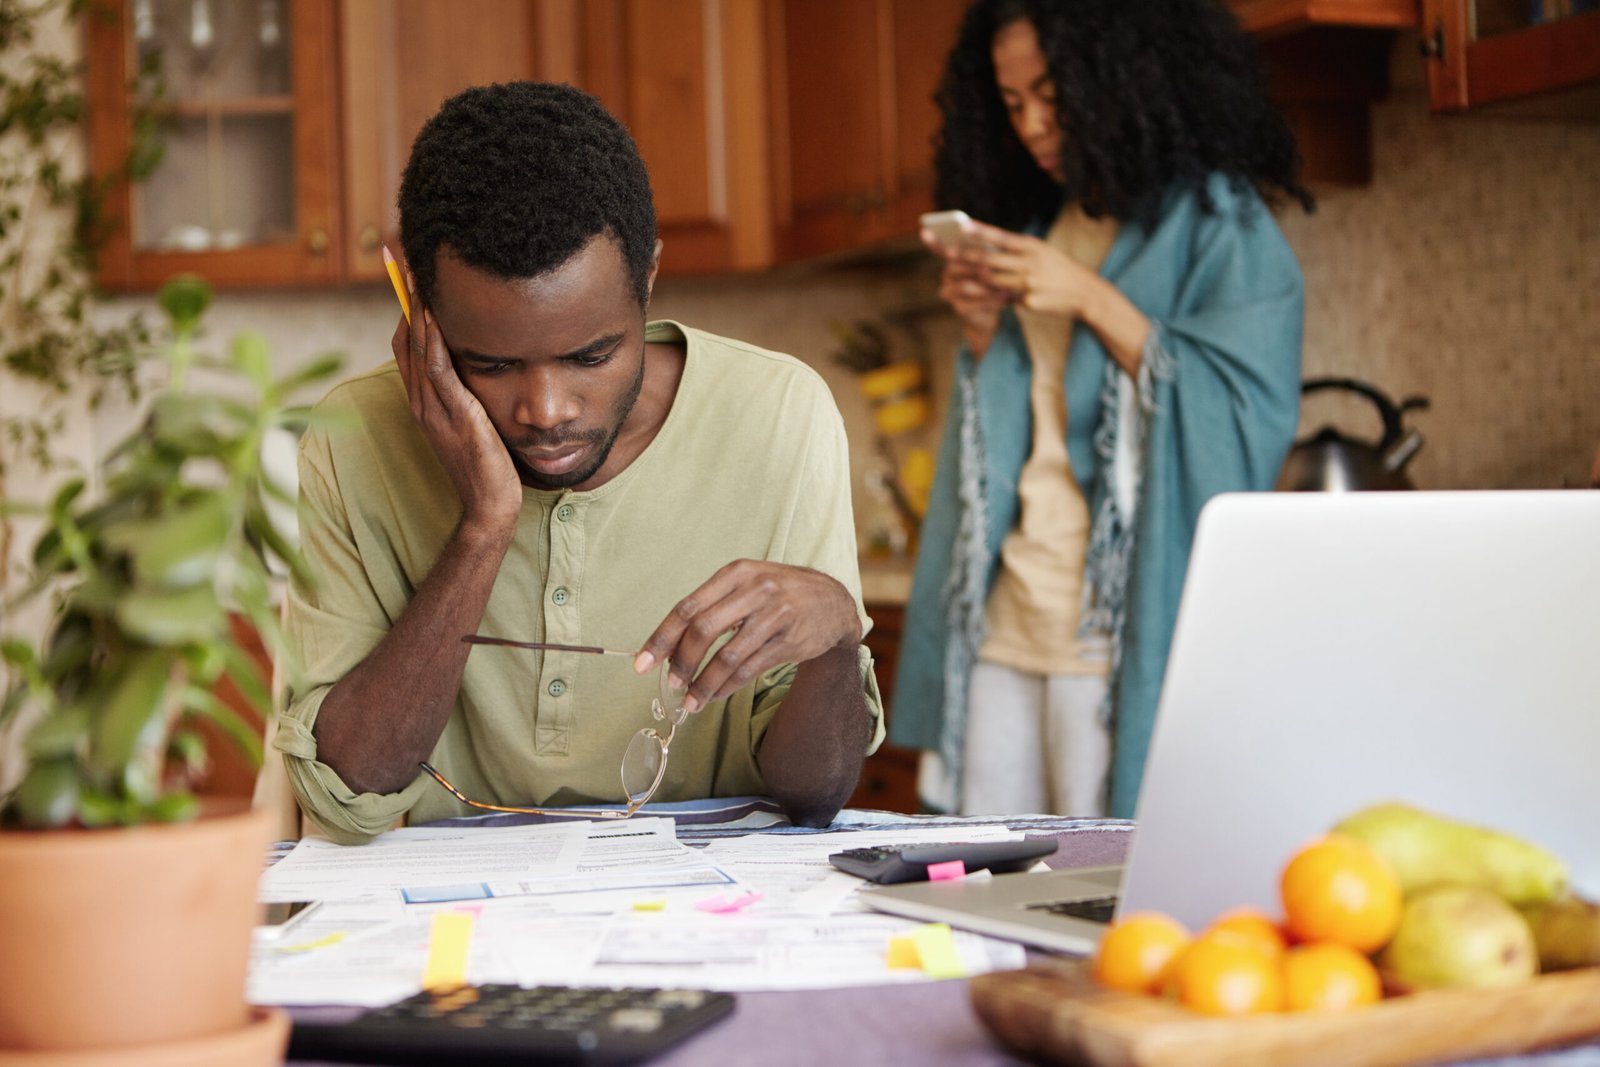
Money is often cited as one of the leading causes of marital tension and household stress. While severe financial crises, such as sudden job loss, can shake a household, it is often the small, ongoing financial habits that do the most long-term damage to family harmony.
Unchecked money habits can breach trust, create resentment, and derail shared goals. Recognising these behavioural patterns early can help families protect both their financial health and their personal relationships.
1. Practice of financial secrecy and hidden spending
Financial infidelity, hiding purchases, keeping secret bank accounts, or lying about income and debts erodes foundation-level trust in a relationship.
- When one partner discovers hidden credit card debts or secret loans, the feeling of betrayal often mirrors non-financial dishonesty.
- Practice full disclosure regarding income, active debts, and individual spending habits. Holding regular, non-judgmental family budget reviews ensures both partners remain informed.
2. Operating without clear financial boundaries for extended family
Generational support and helping extended family members are deeply rooted values in many communities. However, offering financial assistance without clear boundaries or mutual partner consent can put severe strain on the nuclear family’s budget.
- Bailing out relatives continuously or taking on unexpected financial burdens without consulting your spouse often leads to friction and missed household targets.
- Agree as a couple on a set “extended family support budget” each month. Having a predetermined limit allows you to remain generous without compromising your children’s education or family emergency funds.
3. High-lifestyle living fueled by mobile loans and consumer debt
Living beyond one’s means to maintain an image, whether through high-end electronics, frequent dining out, or luxury vacations, often relies on easy-access mobile loans and high-interest credit lines.
- Relying on short-term loans for non-essential lifestyle expenses creates a cycle of constant repayment, leaving zero margin for actual savings or emergency funds.
- Align household spending with actual income rather than social expectations. Prioritise building a three-to-six-month emergency fund before allocating funds to discretionary luxury spending.
4. Unilateral decision-making on major purchases
Making large financial commitments, such as taking out a major loan, entering an investment deal, or purchasing land, without consulting your partner undermines joint decision-making.
- When one partner makes major financial moves independently, the other is left to handle the consequences without having had a voice in the choice.
- Set a household rule where any purchase or financial commitment above an agreed amount must be discussed and agreed upon together before moving forward.
5. Leaving one partner entirely in the dark
Delegating all financial management to one partner while the other remains completely detached creates an unhealthy power dynamic and leaves the uninformed partner vulnerable during unexpected life changes or emergencies.
- If the primary money manager falls ill or passes away, the surviving partner often struggles to locate accounts, manage daily household bills, or track assets.
- Both partners should know where important documents, investment records, insurance policies, and accounts are kept, as well as understand the overall monthly budget.
Fostering a healthy financial environment for your family
Building long-term wealth and family security requires teamwork, open communication, and shared values. By addressing destructive money habits directly and setting clear boundaries together, parents can turn money management from a source of conflict into a tool for building a secure, unified future.
For more, click HERE to join our WhatsApp channel!


Add Comment